Whether a lender would actually fund this - not whether it looks good on paper.
UK buy-to-let lenders don't approve a mortgage because the yield looks healthy. They run an interest coverage ratio test at a stressed rate, and AssetIQ runs the exact same one.
What it does
Stresses the rate, not just today’s
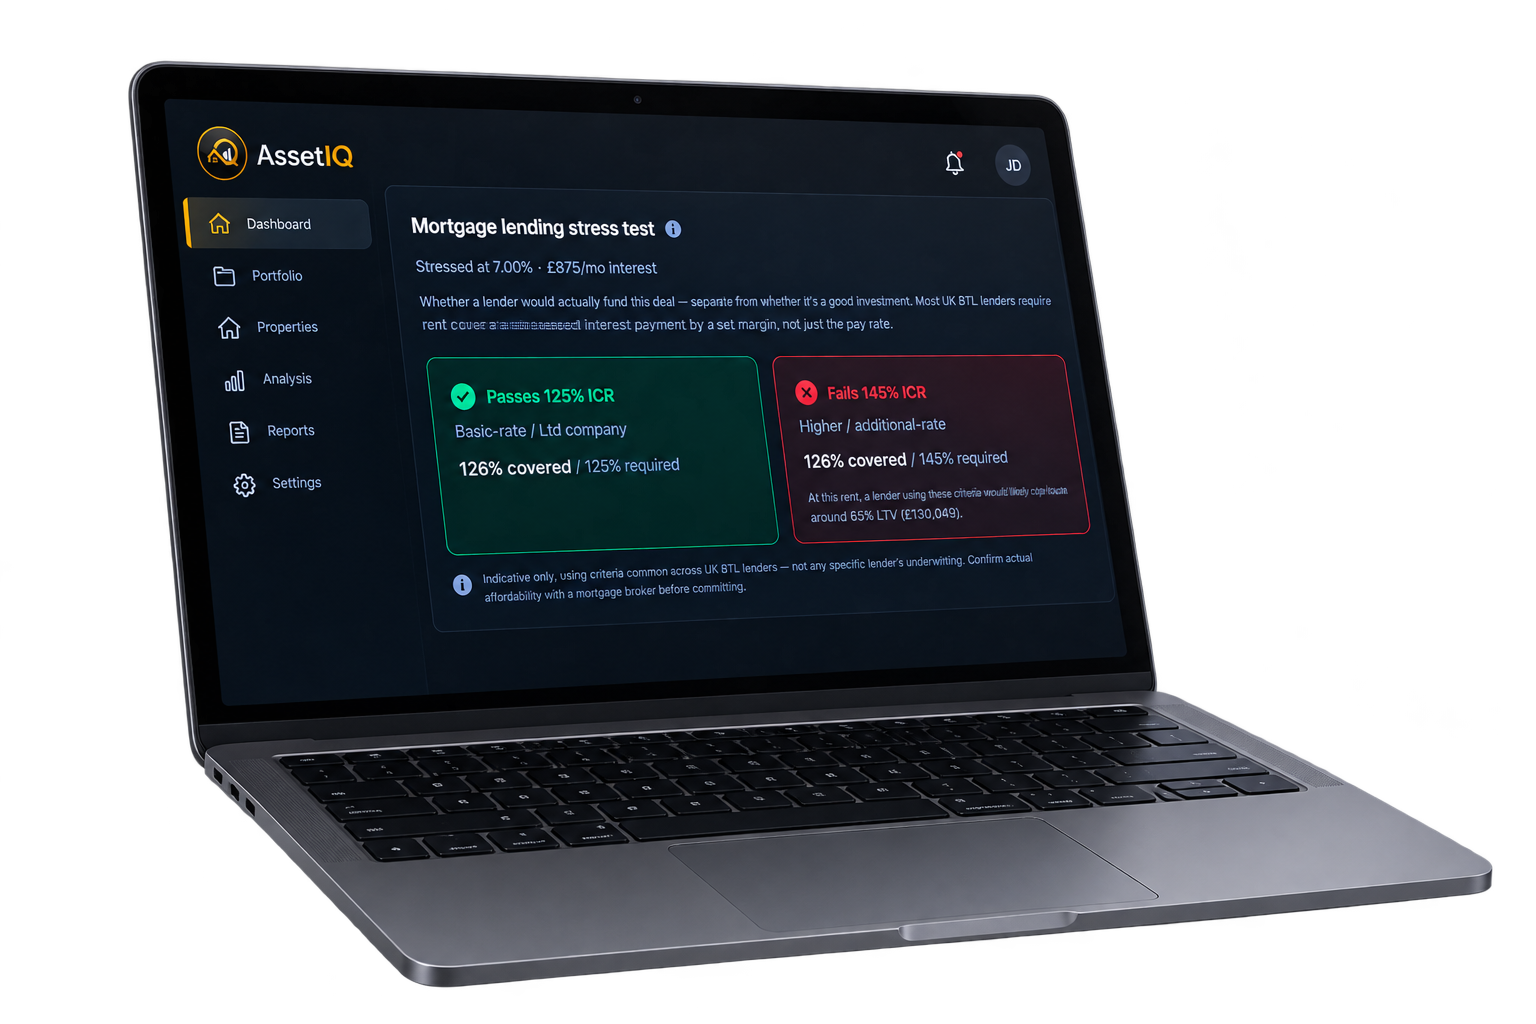
Tests affordability at your pay rate plus 2%, or 5.5% - whichever is higher - the same floor lenders use so a deal isn’t only viable at today’s unusually low rates.
Two bands, because tax status changes the bar
Basic-rate taxpayers and limited companies are tested at 125% coverage; higher and additional-rate taxpayers at 145%, reflecting the real difference Section 24 makes to what you keep.
A genuinely different band for HMOs
HMOs and multi-unit blocks carry their own, higher requirement - shown as a realistic range (130% to 170%), because real lender criteria for these varies far more than a single figure would suggest.
Pass or fail, stated plainly
No ambiguous score - each band shows a clear pass or fail against the real coverage ratio your rental income would need to clear.
How it works
Takes your actual deal
Rent, mortgage amount, and the rate you’d really be offered - not a generic market-average rate substituted in.
Applies the stress rate
Recalculates what the mortgage payment would be at the stressed rate, not the pay rate - the number a lender is actually underwriting against.
Checks coverage against each band
Divides stressed annual rent by stressed annual interest, and checks the result against 125%, 145%, or the HMO range, depending on the property.
Shows you exactly where it stands
Both bands, side by side, so you can see not just whether it passes today’s typical rate but whether it has real headroom if rates move.
Why it matters
A healthy yield can still fail to get funded
Plenty of deals that look fine on gross yield alone don’t clear a lender’s stress test at all - finding that out before you offer, not after, is the entire point.
Tax status genuinely changes what’s fundable
The same property can pass easily through a limited company and fail outright for a higher-rate individual taxpayer - the structure you buy through isn’t a minor detail here.
Rates move; a thin pass today is a real risk
Seeing the actual margin, not just a pass/fail, is what tells you whether a deal has genuine headroom or is one rate rise away from becoming unfundable.
Run a real deal through it and see exactly where it sits against both bands.